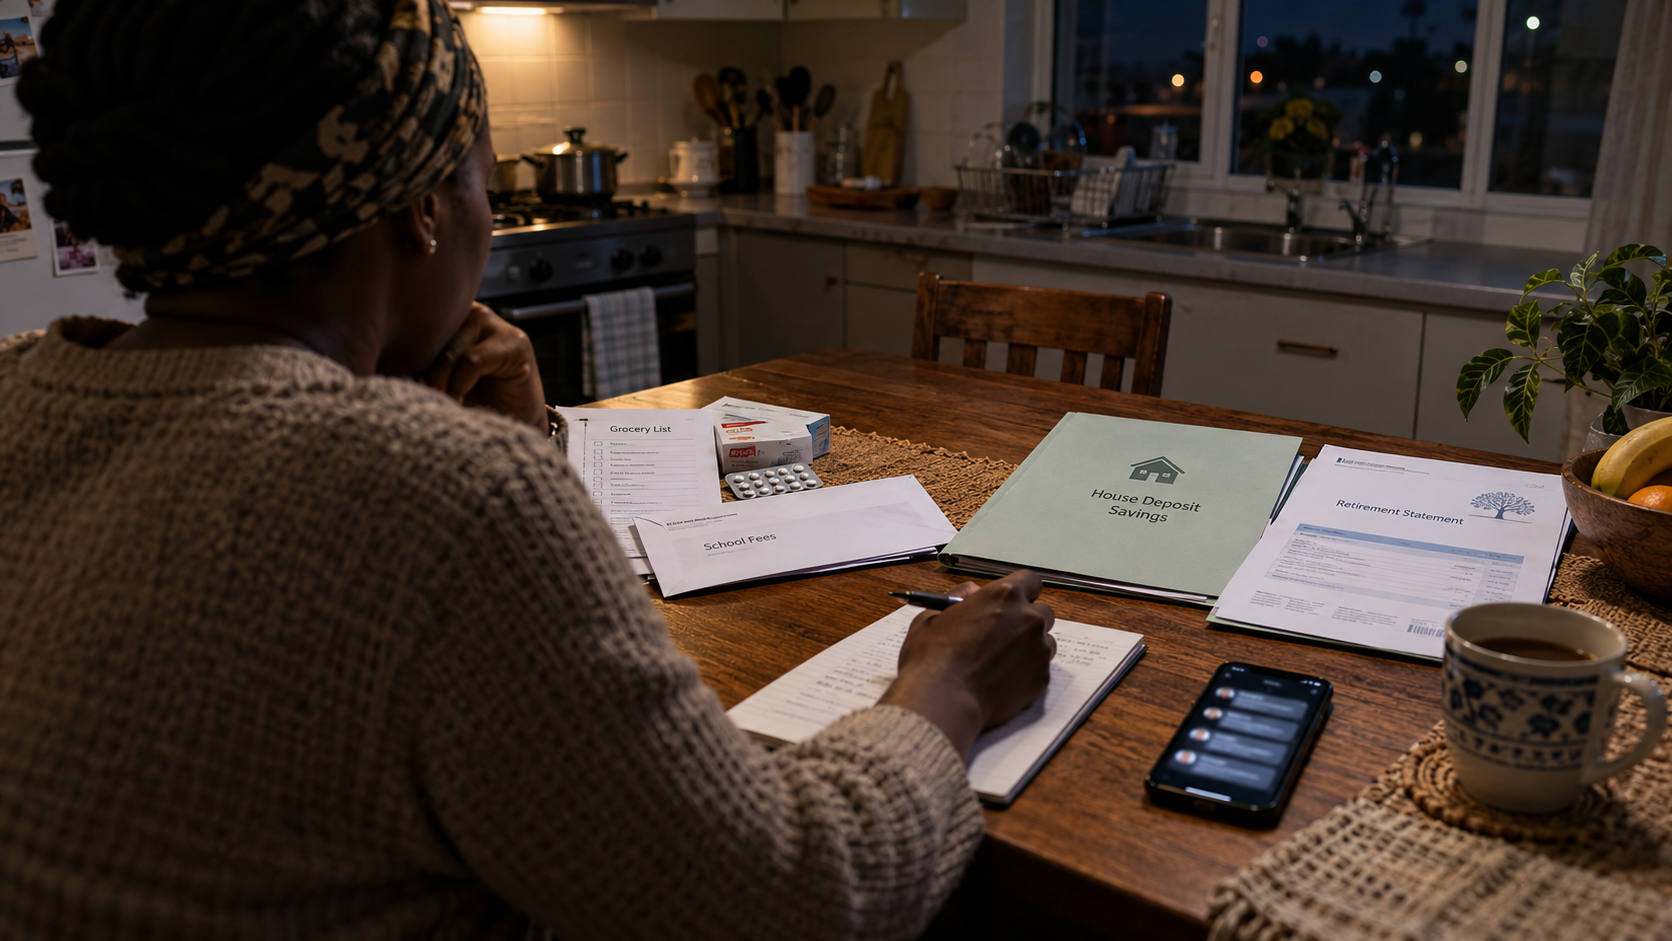
“Black tax becomes generational poverty when every generation is expected to rescue the one before it.”
That was the argument placed before Zimbabweans on Reddit.
The post continued:
“The generation that couldn’t buy their parents houses and cars now expects the most unemployed generation, with the least access to home ownership, to do exactly that.”
The statement touched a familiar anxiety.
A young person gets a job. Before the first payslip has had time to settle, the requests begin.
There is rent at home. Gogo needs groceries. A younger sibling has school fees. Someone is ill. The roof is leaking. An uncle needs help starting a project. A parent has reached retirement without enough income.
One request may be manageable. The problem is that the requests do not arrive as isolated emergencies.
They become a permanent line in the budget.
For some Zimbabweans, that monthly contribution is an expression of love, gratitude and hunhu. It is how families survive when pensions, wages and public services fail.
For others, it is a second tax imposed on the person who appears to be doing slightly better—even when that person is renting, carrying debt and struggling to build a life of their own.
The Reddit discussion exposed the uncomfortable possibility that both descriptions can be true.
“Mari hayinakidze ukayidya uriwega”
One commenter rejected the criticism of black tax as individualism.
“Isu kwedu ticharamba tichichengetana,” they wrote. In our family, we will continue looking after one another.
“Mari hayinakidze ukayidya uriwega.”
Money is not enjoyable when you consume it alone.
The commenter said family support was incorporated into their monthly budget in the same systematic way that other people budgeted for tax. They also claimed to have seen relatives lifted out of poverty one by one through collective support.
That defence of black tax is important.
Not every transfer to a relative represents manipulation. Family money can pay for education, medical treatment, food, agricultural inputs or the small investment that allows another person to start earning.
A young adult may have reached university precisely because older relatives sacrificed for school fees, accommodation and transport. From that perspective, refusing to assist anyone after becoming employed can look less like financial discipline and more like forgetting the network that made one’s progress possible.
The Reddit commenter asked a pointed question: how did the supposedly independent 20-year-old survive the first 20 years of life?
Someone fed that child. Someone paid fees. Someone delayed their own plans.
Why, then, should the hand that was helped refuse to help others?
But parenting is not a loan agreement
Another comment showed how gratitude can be converted into debt.
A contributor described a friend whose father reportedly presented her with a calculation of everything he had spent raising her until the age of 18.
When she reminded him that she had been paying fees for younger siblings, he allegedly replied:
“Handina kukumbira kuti undibatsire.”
I did not ask you to help me.
The friend was advised to answer:
“Neni handina kukumbira kuzvarwa.”
I did not ask to be born either.
The story cannot be independently verified, but it captures one of the most damaging versions of black tax: the belief that ordinary parental responsibility creates a financial invoice that a child must settle in adulthood.
Children can appreciate their parents’ sacrifices without accepting that food, shelter and education were loans.
A parent may reasonably need assistance in later life. That need should still be distinguished from ownership of the child’s future income.
If every school fee becomes a debt and every sacrifice attracts interest, parenting is transformed from a relationship into an investment scheme.
The child is no longer understood as a person whose life should move forward. They become the retirement product.
The generation being asked to pay may own less
One contributor argued that some older Zimbabweans demanding support may actually possess more assets than the children supporting them.
Their parents reportedly owned properties and vehicles without debt after years of formal employment. The children, although living in the diaspora, owned none of those things. Yet the parents still expected them to finance parts of their lifestyle.
This challenges the assumption that the person abroad is automatically wealthier.
A migrant’s income may appear large when converted into United States dollars or rand. The family at home may not see the migrant’s rent, transport, childcare, insurance, visa costs, taxes and debt.
The person sending money may live in a shared house while contributing towards the maintenance of a family property they will never control.
They may help parents retain several assets while remaining unable to save a deposit for their own home.
The pressure is particularly serious for younger workers. If someone spends their twenties and thirties financing previous generations without building savings, investments or retirement income, the family may recreate the same crisis later.
That person eventually becomes the unsupported parent who needs their own children to rescue them.
This is the cycle the original post was warning about.
Zimbabwe did rob many parents of retirement security
The argument becomes unfair, however, when every older person is treated as someone who simply failed to plan.
Many Zimbabweans did save.
Their savings lost value.
The country’s hyperinflation and transition to a multicurrency economy devastated pension funds and long-term savings. A World Bank review found that dollarisation rendered many local-currency pension values virtually worthless, leaving some members with no meaningful pension at all.
Zimbabwe’s Parliament has similarly acknowledged that the 2009 dollarisation period wiped out the savings of many citizens who had reached pensionable age.
The Zimbabwe Human Rights Commission reported in 2025 that older people continued to face a weak and underfunded social-protection system, pension arrears and unresolved historical losses.
A parent may therefore have worked for decades, contributed to a pension and still arrived in old age with very little.
That does not give parents unrestricted access to their children’s earnings. It does explain why some requests cannot honestly be dismissed as irresponsibility.
One Reddit commenter put the immediate problem plainly: their grandmother needed a solar panel now.
Anger at whoever destroyed the pension would not charge her phone tonight. Political accountability mattered, but the family still had an urgent need within its power to solve.
This is where abstract arguments about personal responsibility collide with the reality of someone you love sitting in darkness.
Is family support replacing the government?
Another side of the debate argued that black tax allows institutional failure to become normal.
Why must a grandchild buy Gogo’s solar panel?
What happened to her pension?
Why are families paying individually for problems that should be addressed through reliable pensions, employment, healthcare, education and social assistance?
Zimbabwe’s problem is not only that relatives ask for money. It is that family networks have become an informal welfare system.
The World Bank describes Zimbabwe as having endured prolonged economic volatility, high informality, rising poverty and low coverage of social assistance.
Research on the country’s social-protection system has estimated coverage at only 22% for older people and pension-scheme coverage at 18.9% of the labour force.
Under such conditions, refusing family support does not automatically produce a functioning public safety net.
It may simply leave Gogo without food.
But quietly filling every gap can also conceal the scale of public failure. A government faces less immediate pressure when school fees, medical bills, elder care and unemployment are continually absorbed by employed relatives and the diaspora.
Families are forced to choose between two unsatisfactory responses:
Help now and risk perpetuating the system.
Or refuse now in the hope of forcing accountability, while a relative suffers in the meantime.
Most people will choose to help the person they can see.
Helping family is not necessarily black tax
Part of the disagreement comes from using one phrase to describe very different arrangements.
Black tax can refer to:
- Buying groceries for an elderly parent whose pension was destroyed.
- Paying school fees for a younger sibling.
- Supporting a relative through a genuine emergency.
- Financing several able-bodied adults indefinitely.
- Being expected to provide luxury goods because one lives abroad.
- Paying family expenses while being denied any say over the assets being maintained.
- Repaying relatives who previously funded one’s education.
- Being treated as selfish whenever one attempts to save.
These are not morally or financially equivalent.
A transfer that helps a sibling qualify for a profession may expand the family’s earning capacity. A recurring payment that enables an able-bodied relative to avoid work may create dependency.
Buying medication for a parent is different from financing appearances, ceremonies or lifestyle upgrades.
Research on familial financial support cautions against portraying it only as a burden. Such support can express Ubuntu, solidarity and responsibility while providing real fulfilment to the person helping. It also becomes necessary where poverty is high and state assistance is inadequate.
The useful distinction may be between family investment, family protection and family extraction.
Family investment builds another person’s ability to stand.
Family protection responds to needs such as age, illness, disability or crisis.
Family extraction continues because one person’s income has become available for everyone else’s wants, without limits, transparency or a plan for reducing dependence.
Calling all three “black tax” hides the difference.
Gratitude cannot require self-destruction
The defender of monthly support asked how a person stops poverty by being “stingy”.
The critic’s answer was that a 20-year-old worker must support their present needs, save for the future, prepare to buy a home and eventually raise the next generation.
That is not necessarily selfishness.
Savings are how a person avoids imposing the same burden on their future children.
A retirement contribution may look like money withheld from the family today. It can also be the money that prevents the family from having to support that person 30 years later.
An emergency fund may mean declining one request now. It can prevent the household from collapsing when employment is lost.
A housing deposit may appear less urgent than a relative’s immediate wants. But without asset accumulation, the supposedly successful family member remains permanently vulnerable.
The problem is not that people help.
It is that the person helping is sometimes forbidden from reaching the point where they no longer need help themselves.
Boundaries are not abandonment
The Reddit debate frequently presented only two choices.
Either share everything with the family or embrace selfish individualism.
Families need a third option: structured solidarity.
That could mean deciding in advance how much can be contributed each month instead of responding emotionally to every request.
It could mean prioritising food, health, education and genuine emergencies over luxury purchases.
It could mean paying a provider directly where necessary rather than sending unaccounted-for cash.
It could mean assisting an unemployed relative for a defined period while agreeing on what they will do to begin earning.
It could mean siblings sharing responsibility instead of directing every problem towards the person abroad.
It could also mean parents disclosing their assets, debts and income honestly before asking children for support.
The person contributing must also be allowed to save.
A family plan that consumes the contributor’s retirement, housing and children’s needs has not defeated poverty. It has postponed it.
The question is what the money produces
Black tax is often discussed as though the amount sent is the only issue.
The more important question is what happens after the transfer.
Did the money educate someone who later became self-supporting?
Did it keep an elderly parent safe?
Did it fund a business with records and a realistic plan?
Did it repair an asset that benefits the wider family?
Or did it disappear into repeated emergencies without changing anyone’s position?
One commenter claimed that systematic family support had lifted relatives “member by member”. If that is true, the payments functioned as an informal development system.
But where the same contributor is still carrying the same adults years later—with new requests added as soon as old ones are settled—the system is not graduating anyone from dependency.
Support should ideally reduce future need.
When it only maintains need, the family must be willing to examine why.
A national failure enters the family WhatsApp group
The black-tax argument is often framed as a battle between selfish children and entitled parents.
That framing is too small.
Behind the family conflict sit decades of inflation, lost pensions, informal work, weak social assistance, expensive healthcare, unemployment and limited access to affordable housing.
Economic failure reaches the household as a personal message:
“Can you send something?”
The sender may be asking because they made poor decisions.
They may also be asking because a pension disappeared, a job ended, a harvest failed or medical treatment cannot wait.
The recipient may refuse because they do not care.
They may also refuse because they are one transfer away from missing rent.
Neither a bank balance nor a diaspora address tells the complete story.
“Chirere chigokurerawo” cannot be the only retirement policy
Zimbabwean culture values reciprocity: raise a child and, in time, that child may help sustain you.
The proverb carries warmth when it describes gratitude freely given.
It becomes dangerous when interpreted as a financial contract under which children exist to finance their parents.
A functioning family should allow resources to move in more than one direction and across more than one moment.
Adults help children.
Working relatives assist those in crisis.
Those who receive opportunities eventually help others.
Older people contribute knowledge, care, land, housing or whatever resources they possess.
And the younger generation is allowed to accumulate enough to support its own children without beginning again from zero.
That is different from assigning every generation the same impossible task: rebuild the previous generation before building anything for itself.
Black tax is not automatically the poverty cycle—or the solution
The Reddit argument cannot be settled with a universal rule.
Stopping all family support would expose elderly people, children and unemployed relatives to severe hardship. For many Zimbabwean households, the extended family remains the most reliable form of social protection available.
But unlimited support can also destroy the financial future of the person providing it.
The line is not between African solidarity and Western individualism.
It is between assistance that strengthens a family and obligation that consumes one member until another rescue is required.
Perhaps the most useful question is not:
“Should I support my family?”
It is:
“Does the way we support one another leave the next generation stronger than the last?”
If the answer is no, then the family may not be defeating poverty.
It may only be passing the invoice forward.